
If you grew up in Nagpur, you know our city has always valued stability and a steady approach to life. For decades, the financial roadmap for many households in Vidarbha was fairly simple: work hard, save money in bank Fixed Deposits (FDs), buy physical gold during Dhanteras or weddings, and perhaps invest in a plot of land around Wardha Road, Besa, or other growing areas of the city.
It was a familiar and understandable approach to building financial security.
That mindset protected generations, and there is genuine wisdom in valuing safety and financial stability. But Nagpur is changing rapidly. With infrastructure development, the expansion of business and technology opportunities around MIHAN, and changing career and lifestyle aspirations, the financial landscape is evolving too.
The traditional approach isn’t necessarily wrong. But relying on only a few familiar avenues may not be enough to address today’s financial goals, inflation, and long-term wealth creation.
The Financial Realities Many Nagpur Families Face
Whether you run a business in Itwari or Gandhibagh, work in IT, healthcare, manufacturing, or operate a growing professional practice, many families face similar financial questions.
“My money is safe in FDs, but is it actually growing?”
Fixed Deposits can provide stability and predictable returns. However, when inflation and taxes are considered, the actual growth in purchasing power may be considerably lower than the headline interest rate.
This is why financial planning involves looking beyond where your money is currently parked and asking whether your overall strategy is aligned with your long-term goals.
“How do I balance today’s needs with my retirement?”
For business owners, reinvesting profits into the business can naturally take priority. For salaried professionals and families, children’s education, home purchases, lifestyle expenses, and other immediate priorities can compete with retirement savings.
The challenge is not simply saving more. It is creating a structure where today’s requirements and tomorrow’s goals can coexist.
“Real estate and gold are familiar, but are they liquid when I need money?”
Gold and property have traditionally been important parts of wealth for many Indian families. They can serve different purposes within a financial plan.
However, converting an asset into cash at the exact time you need it may not always be simple. Selling property can take time, while selling physical gold may involve practical considerations and price differences.
This is why liquidity and diversification matter when building a financial strategy.
A Modern Approach to Financial Planning in Nagpur
Financial planning isn’t about taking unnecessary risks or investing in complicated products you don’t understand.
It is about creating a structured strategy around your goals, time horizon, financial position, and risk profile.
Instead of asking, “Which investment should I buy?”, a better starting point can be:
“What am I investing for, and how should my money be structured to support that goal?”
Here are some important building blocks of a modern financial plan.
1. Build a Strong Financial Safety Net First
Before focusing heavily on long-term investments, your financial foundation needs attention.
This can include maintaining an adequate emergency fund covering around 3–6 months of essential expenses, depending on your circumstances, along with appropriate health and life insurance.
An emergency fund provides liquidity when unexpected expenses arise, while insurance helps protect your long-term financial plan from major financial shocks.
Your financial plan should not depend entirely on your investments being available at the exact moment an emergency occurs.
2. Create a Balanced Asset Allocation
Different assets serve different purposes.
A well-structured financial plan considers how much should be allocated across different asset classes based on your goals, time horizon, and risk profile.
Fixed Income
Fixed-income investments can provide stability and may be useful for short- and medium-term requirements where capital stability and liquidity are important considerations.
Equity Mutual Funds and SIPs
For long-term goals, equity-oriented investments can provide an opportunity for growth and compounding. SIPs can help investors invest systematically rather than depending entirely on market timing.
However, the appropriate allocation depends on the goal, investment horizon, and an individual’s ability and willingness to take risk.
Gold and Property
Gold and property can have a place in a diversified portfolio, depending on an individual’s circumstances and objectives.
The key is to avoid allowing familiarity with a particular asset to determine the entire investment strategy.
3. Invest According to Your Goals, Not Market Hype
Instead of investing simply because a particular asset or market trend is popular, connect your investments to specific financial goals.
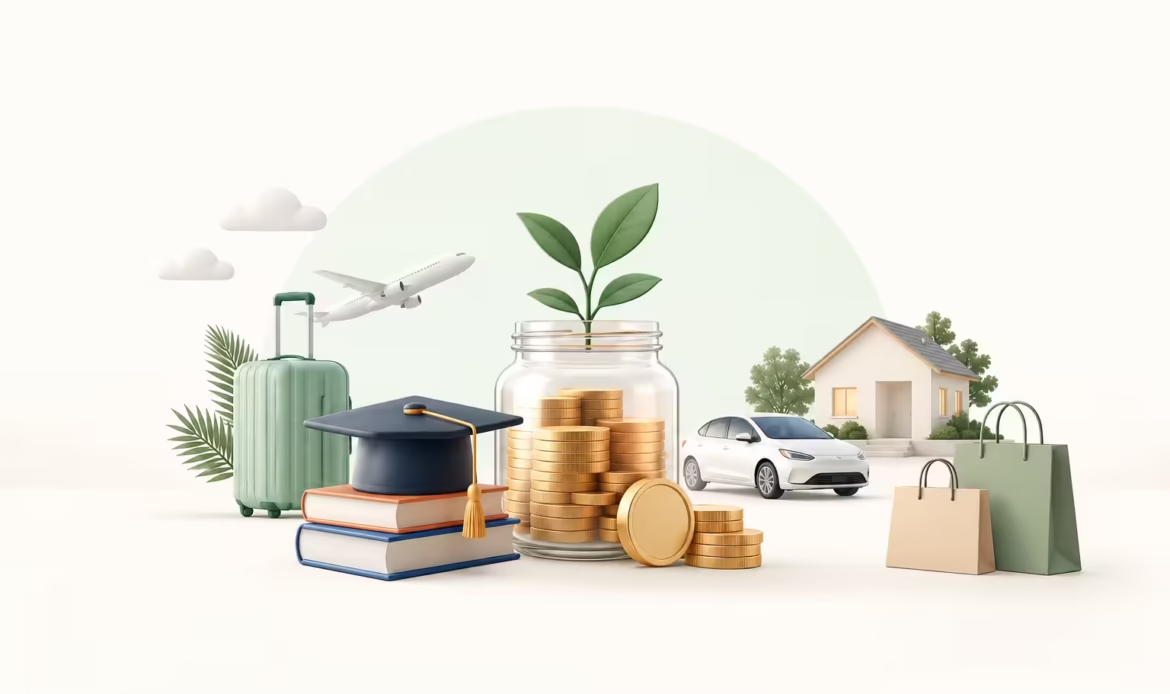
Short-Term Goals — 1 to 3 Years
Examples may include:
- Children’s school fees
- Planned vacations
- Near-term purchases
- Business working capital
- Other upcoming financial commitments
The focus for these goals is generally on appropriate liquidity and managing the risk of significant capital fluctuations.
Medium-Term Goals — 3 to 7 Years
These may include:
- Home down payment
- Business expansion
- Higher education
- Major family expenses
The investment approach can be structured according to the specific timeline and risk that the goal can accommodate.
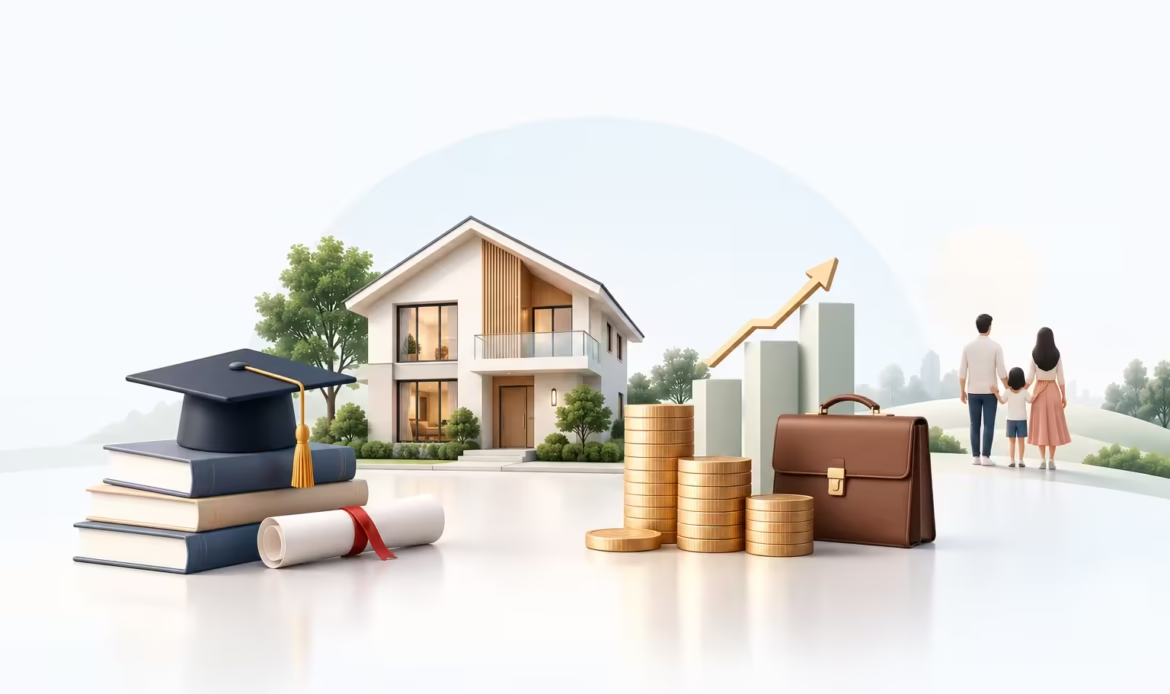
Long-Term Goals — 7+ Years
Long-term goals may include:
- Children’s higher education
- Children’s marriage
- Wealth creation
- Financial independence
- Retirement
With a longer investment horizon, investors may have greater flexibility to consider growth-oriented assets, while still align
Financial Planning Is More Than Choosing Investments
A financial plan is not simply a list of mutual funds, FDs, or other investments.
It connects different parts of your financial life.
Your income, expenses, investments, insurance, taxes, liabilities, children’s education, retirement, and other major goals can all influence one another.
For example, deciding to purchase a home can affect your emergency fund, insurance requirements, monthly cash flow, and ability to invest for retirement.
This is why holistic financial planning can be useful for families who want to look at their finances as one connected picture rather than managing each investment separately. Pranamya describes its approach as covering areas including investments, insurance, tax, retirement and long-term wealth creation.
From Saving Money to Planning It With Purpose
For many Nagpur families, saving has always been an important part of financial life.
The next step is to make those savings purposeful.
Instead of simply asking:
“Where should I keep my money?”
Consider asking:
“What should this money help me achieve?”
That shift-from simply accumulating money to planning it around specific goals—can make financial decisions more structured and easier to review over time.
Let’s Have a Conversation
Financial planning doesn’t need to begin with complicated spreadsheets or lengthy financial reports.
It can start with a simple conversation about where you are today, where you want to be in the future, and what financial goals matter most to you.
Whether you want to review your existing investments, understand whether your current portfolio aligns with your goals, start investing systematically, or build a comprehensive financial plan for your family, a structured approach can help bring greater clarity to your financial decisions.
Your money should have a purpose. Your financial plan should help you work towards it.
If you’re looking for financial planning in Nagpur, Pranamya Financial Services provides fee-only financial planning and investment advisory services designed around individual goals, risk profiles, and long-term financial needs.